
Interest-Free Instalments: A UK Guide for Luxury Fashion Buyers
Interest-free instalments are a genuinely useful way to buy luxury fashion in the UK, provided you meet the provider’s terms and pay on schedule. The 0% promise is real, but it is conditional: miss a due date or misread the fine print, and fees or interest can quietly change the arithmetic of what felt like a straightforward purchase.
Before you confirm any order split into payments, do two things.
Read the instalment partner’s terms, especially the late fee structure and whether interest applies to your specific plan.
Check the retailer’s returns policy so you know exactly how a refund is processed if the piece does not work out.
Get those two details right, and instalments become a sensible tool for managing the cost of a beautifully made handbag or a considered new coat. Get them wrong, and a £600 dress can end up costing more than the price tag suggested.
Key Takeaways
Interest-free instalments stay genuinely free only when you pay on time and understand the provider’s terms before you check out.
Point | Details |
Confirm the plan type | Pay-in-3 or pay-in-4 is typically 0% on time; longer financing may carry APR. |
Read the fee structure | Check late fee amounts and caps before confirming any instalment plan. |
Verify the returns process | Confirm who issues refunds and whether instalments continue during a return. |
Watch your repayment source | Automatic debits can trigger overdraft or failed payment fees if funds run short. |
Shop with Vivienlauren | Vivienlauren offers interest-free instalments at checkout with clear returns and delivery terms. |
Table of Contents
How Interest-Free Instalments Actually Work
Most UK buy-now-pay-later plans fall into two categories, and the difference matters enormously once you are spending real money on a designer piece.
Short-term pay-in-3 or pay-in-4 plans. You pay a portion at checkout, then the remaining instalments every two to four weeks. These are typically interest-free by design, not by promotion, as long as every payment lands on time.
Longer monthly financing. Spread across several months or up to 24 months, these plans sometimes carry an annual percentage rate (APR), especially past an initial interest-free window. Klarnoa UK offers both structures, with financing extending to two years and interest applying only to the financed portion when that option is selected.
Here is the mechanics that surprises a lot of first-time users: the retailer gets paid in full, upfront, by the instalment provider. You are not repaying the boutique. You are repaying the finance company, which is why the provider’s terms, not the shop’s, govern your fees and credit exposure.
A concrete example: Take a £600 dress. Split across a pay-in-3 plan, you would pay roughly £200 at checkout and £200 at each of the next two intervals, with no interest if every payment clears on schedule. Put that same £600 onto a 12-month financed plan instead, and depending on the provider’s rate, you could pay considerably more than £600 by the time the balance is settled. Personal finance research from NerdWallet notes that pay-in-four plans are usually 0%, while longer financing can run APRs up to the mid-30s.
Enrollment also varies. Some providers run a soft credit check that does not affect your score; others, particularly for larger financed amounts, may require a fuller assessment. Always confirm which applies before you commit to a plan on a high-value item.
What to Check in the Small Print Before You Buy
The difference between a smart instalment purchase and a costly one usually comes down to five details buried in the terms and conditions. None of them takes more than a minute to check, and all of them affect the final price you actually pay.
Late fees. Ask whether they are a flat amount or a percentage, and whether there is a cap. The CFPB notes that BNPL loans commonly charge late fees, and the structure differs meaningfully between providers.
Credit reporting. Some providers report missed payments to credit reference agencies, which can affect your score and your ability to get financing later. Confirm this before assuming a missed instalment is a private matter between you and the app.
Autopay risk. Automatic repayments taken from a debit card can trigger overdraft charges or failed payment fees if the account does not have sufficient funds on the due date. Consumer guidance from the FTC flags this as a common and avoidable cost.
Hidden service fees. A required down payment or processing fee changes the effective cost of what you assumed was a 0% deal, so read the checkout summary line by line.
Pro Tip: Screenshot the repayment schedule the moment you check out. If a dispute ever arises over a fee or a missed date, having the original terms saved is far more useful than trying to reconstruct them from memory weeks later.
Weighing the Pros and Cons for High-Value Fashion
Instalments genuinely change what is possible for a considered luxury purchase, but they are not a neutral convenience. They carry real trade-offs worth naming honestly.
The upside:
Smoother cashflow around a single large purchase, rather than one painful debit.
The ability to secure a limited-run piece, such as a handcrafted leather bag, before it sells out, while spreading the cost.
A practical way to manage fit and feel for clothing before the full balance is due.
The downside:
The ease of splitting payments can tempt you into spending beyond what you would commit to in one transaction.
Returns on instalment purchases sometimes take longer to resolve, and you may need to keep paying until the refund clears.
Late fees hit disproportionately hard on expensive items, since fees are often calculated relative to the amount owed.
Instalments work best for planned, budgeted purchases where you have already decided the piece earns its place in your wardrobe. They work poorly for impulse buys or anything with unclear return terms.
Using Interest-Free Instalments Safely: A Step-By-Step Checklist
Treat every instalment purchase on a luxury item with the same discipline you would apply to a larger financial decision, because that is effectively what it is.
Before you buy: Confirm the retailer’s returns window and process, calculate your total outflow across every instalment, and note each due date on your calendar.
Compare your options: Weigh a shorter interest-free plan against a longer financed one, and check whether any fees apply regardless of which you choose.
At checkout: Select the plan that fits your actual budget, not the one with the smallest first payment, and review the full repayment calendar before confirming.
Save your records: Screenshot the terms, the repayment schedule, and your order confirmation the moment the purchase completes.
After delivery: Open the item immediately and check it against the description and photos. If something is wrong, start the return process without delay through a channel like Vivien Lauren ’s returns notification form.
Track your payments: Keep receipts for every instalment and confirm each one clears on the scheduled date.
If a dispute arises: Document every email and message with the retailer or provider, use the retailer’s official returns channel first, and escalate to a consumer protection body if it remains unresolved.
Pro Tip: Set a calendar reminder two days before each instalment is due, not on the day itself. That buffer gives you time to top up an account before an automatic payment fails.
How Major UK BNPL Providers Handle Higher-Ticket Purchases
Terms differ enough between UK providers that it is worth checking the specifics rather than assuming one plan mirrors another. Klarna UK offers both interest-free pay-in-3 instalments and financing extending up to 24 months, with interest applying only to the financed portion and late fees triggered by missed payments. Other UK providers follow a broadly similar structure: a short interest-free tier for smaller, quicker splits, and a longer financed tier for larger purchases where an APR may apply.
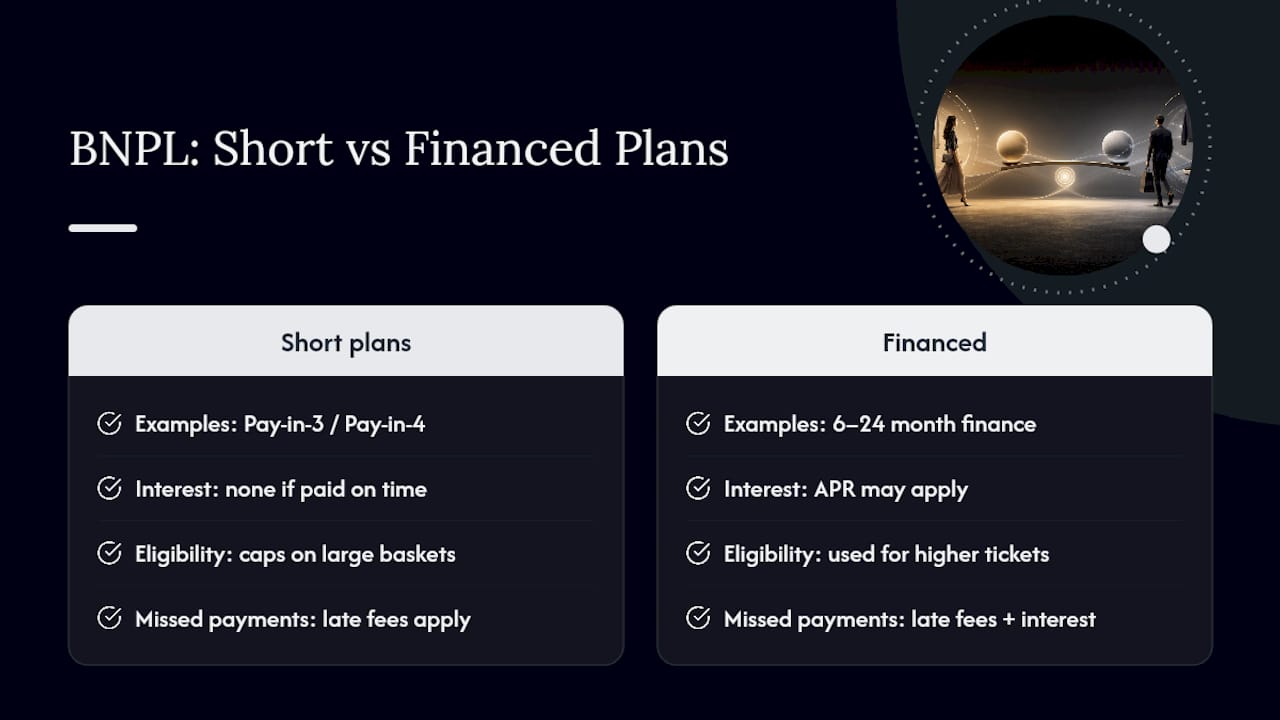
For a luxury item priced in the hundreds of pounds, the practical question is less “which provider” and more “which plan length.” A pay-in-3 or pay-in-4 option keeps the purchase interest-free as long as you pay on time, which suits a considered, one-off buy like a designer bag or an occasion dress. A financed plan stretching across many months makes sense only if you have compared the total repayable amount against the sticker price and are comfortable with the difference.
Eligibility can also shift with basket size. Providers sometimes cap the amount available on their zero-interest short plans, pushing higher-value purchases toward financed options by default. Before assuming a £900 coat qualifies for the same interest-free structure as a £150 blouse, check the plan options actually presented at checkout rather than what a provider advertises broadly.
Can Instalments Help Build Your Credit History?
Used carefully, instalment plans can support your credit profile, but the relationship is not automatic. Many short-term pay-in-3 or pay-in-4 plans in the UK do not report on-time payments to credit reference agencies at all, so paying flawlessly on one of these may do little to build your file. Where reporting does happen, it tends to run in one direction that matters most to you: missed payments are more likely to be reported than perfect ones, according to guidance from the CFPB.
The safest approach treats every instalment plan as if it could affect your credit file, whether or not the provider currently reports. That means never taking on a plan you would struggle to repay even in a tight month, keeping your total outstanding instalment debt visible in your own budget rather than scattered across apps, and paying every due date on time as a matter of habit. Over time, that discipline protects your ability to access financing for genuinely important purchases, whether that is a mortgage application or a future luxury piece bought the same considered way.
Vivien Lauren’s Interest-Free Instalments for Considered Purchases
Vivien Lauren offers interest-free instalments at checkout, giving you a straightforward way to bring home a handcrafted leather bag or a beautifully cut dress without committing the full amount in one payment.

The site is built to make that decision easier before you even reach checkout. Every piece, from the dresses to the bags, comes with detailed imagery and description so you know precisely what you are buying, which matters enormously when fit and craftsmanship are the whole point. UK and international orders over qualifying orders ship free, and the site’s returns policy spells out exactly how a refund is handled if a piece does not suit you.
Choosing instalments at checkout takes a moment: select the payment option, review the schedule presented, and confirm. Save the order confirmation and a screenshot of the repayment terms as your record, the same discipline worth applying to any instalment purchase. From there, browse the current dress collection or explore the shoes if you are shaping a full look, and let the instalment option carry the cost across a few weeks instead of one.

A Personal Note on Buying Well, Not Just Buying More
We think of instalments as a budgeting tool, never as permission to spend beyond what you have actually planned for. The best use of a payment plan is on a piece you already know you will keep: something handcrafted, well made, and built to outlast a season. Spread the cost. Never spread the commitment thin.
Sources
FAQ
Is BNPL Actually Interest-Free in the UK?
Short-term pay-in-3 and pay-in-4 plans are typically interest-free if every payment is made on time, but longer monthly financing options can carry APR, as Klarna UK confirms for its own plans.
Does Using Instalments Affect My Credit Score?
It depends on the provider. Some do not report short-term plans to credit reference agencies at all, while others report missed payments, which can affect your score, according to the CFPB.
What Happens if I Return an Item Bought on Instalments?
The refund process depends on the retailer and provider, so check whether the retailer or the instalment company issues your refund and whether you must keep paying until it clears. Vivien Lauren’s returns policy outlines this clearly for orders placed on the site.
Are There Fees for Missing a Payment?
Yes, most BNPL providers charge late fees for missed payments, and some cap the amount while others do not, so it is worth checking before you commit to a plan on a high-value item.
Does Vivien Lauren Offer Interest-Free Instalments?
Yes, Vivien Lauren offers interest-free instalments at checkout alongside free UK and international shipping on qualifying orders, giving shoppers a clear, brand-backed way to spread the cost of a luxury purchase.
Recommended
This fashion guide has been
authored and brought to you by Nancy. On behalf of Vivien Lauren. Vivien Lauren. Luxury. Craftsmanship. That's Proudly Italian. Vivien Lauren. Proud To Style.

